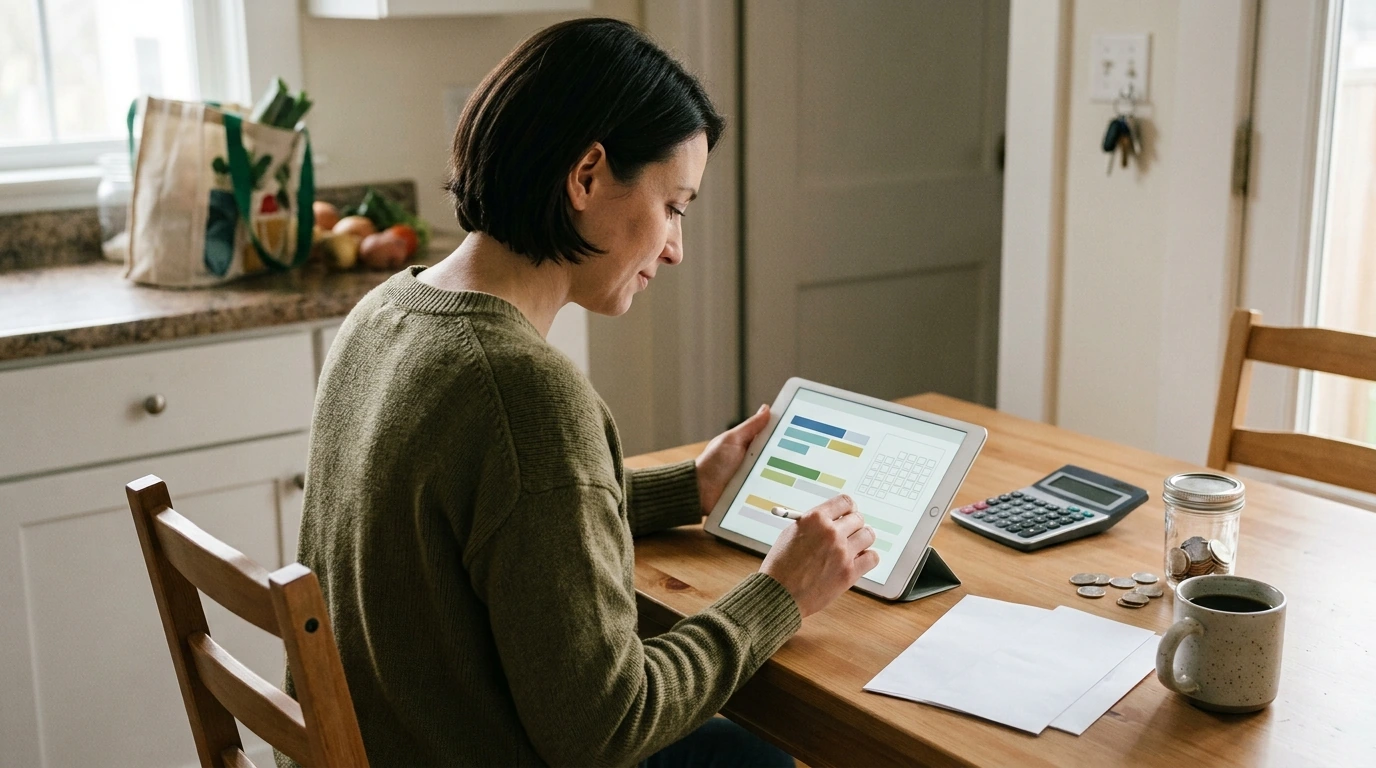
A good budget is less about restriction and more about clarity: knowing what’s coming in, what must go out, and what goals matter most. A simple system can lower stress fast—especially when it’s built around real numbers, a few protective buffers, and a rhythm you can repeat even on busy weeks.
Before categories and spreadsheets, decide what the next 30–90 days need to accomplish. Pick one or two outcomes that would instantly reduce pressure—like stopping overdrafts, catching up on bills, paying off one card, or building a starter emergency fund.
Start with a clean list of every income source and its schedule: paychecks, side gigs, benefits, child support, or any recurring transfers. What matters most isn’t “average income,” but “income you can safely count on.”
If your paycheck withholding feels off (too big a refund or a surprise tax bill), the IRS Tax Withholding Estimator can help you dial it in without guessing.
A budget breaks when bills arrive earlier than expected. Build a simple bills calendar first—then decide what’s left for groceries, gas, and fun.
More categories don’t create better budgeting—more friction does. For most households, 10–15 categories total is plenty.
| Category | What it covers | Suggested target | Stress-reducer tip |
|---|---|---|---|
| Housing + utilities | Rent/mortgage, power, water, internet | 25–40% | Set utility averages; keep a small overage buffer |
| Food | Groceries, limited dining out | 10–15% | Plan 3–5 default meals; cap restaurants weekly |
| Transportation | Fuel, transit, maintenance | 10–15% | Create a maintenance sinking fund |
| Debt minimums | Credit cards, loans | As required | Pay minimums first; automate to avoid fees |
| Savings | Emergency fund, goals | 5–20% | Start with a small autopay; increase monthly |
| Lifestyle | Entertainment, shopping, hobbies | 5–15% | Use a weekly allowance to prevent overspend |
| Sinking funds | Gifts, annual renewals, medical | 3–10% | Divide annual costs by 12 and save monthly |
The best tracking method is the one you’ll still use next month. Pick one primary tool and keep the routine simple.
For more budgeting templates and basic financial education, the Consumer Financial Protection Bureau’s budgeting resources are a solid reference.
If you want a ready-made structure for the reset (prompts, checklists, and category templates), a guided workbook can reduce decision fatigue. A practical option is Budget Like a Boss: Your Step-by-Step Guide to Mastering Money Without the Stress (Digital Download PDF).
For a separate, quick-hit planning tool that pairs well with money routines, Your Ultimate Young Leader’s Power Checklist | How to Be a Young Leader Digital Download can help keep weekly goals and habits organized alongside your budget reset.
For additional free, foundational money education, the FDIC Money Smart program is another reliable resource.
A simple category-based plan with a weekly spending limit is usually easiest. Start from real past spending, keep categories minimal, and add a small buffer so one unexpected cost doesn’t derail the whole month.
Use a conservative baseline based on your lowest typical month, fund essentials first, and put “extra” income into sinking funds and a one-month buffer. Once the buffer is built, you can direct surplus toward goals like debt payoff or savings.
A small starter emergency fund helps prevent new debt when surprises happen. After that, a balanced approach often works best: pay minimums on all debt, target extra payments to one priority balance, and keep some savings going.



Leave a comment