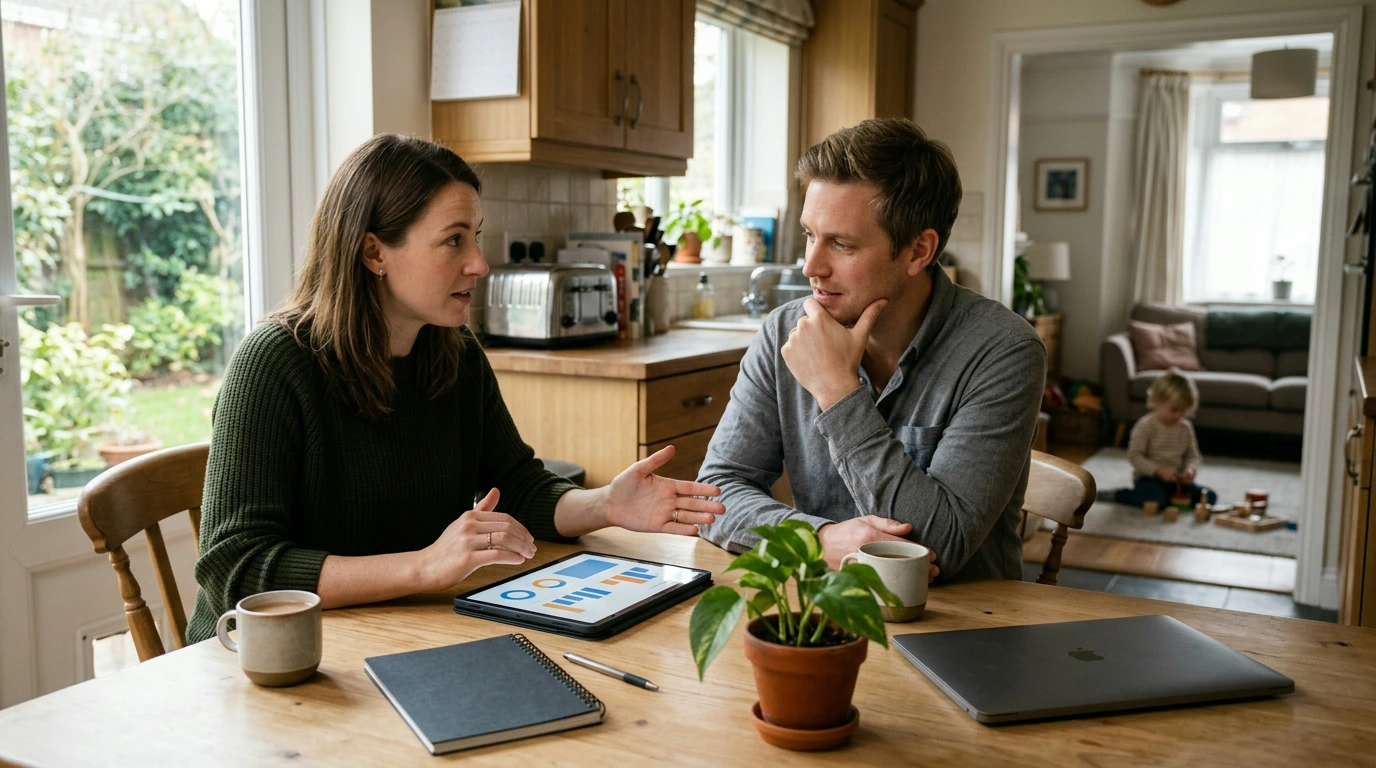
Your 30s often bring higher earning power, bigger responsibilities, and clearer priorities. That combination makes this decade a strong launchpad for building wealth that lasts beyond one lifetime. The path is less about one “perfect” investment and more about a repeatable system: stabilize cash flow, eliminate expensive debt, invest consistently, protect what you build, and document a plan that transfers assets smoothly.
Generational wealth is less about flashy net-worth numbers and more about durable outcomes: financial security, optionality, and the ability to support future family goals such as education, housing stability, entrepreneurship, and charitable giving.
It also helps to separate wealth from income. A higher salary can accelerate progress, but net worth grows when saving and investing stay ahead of lifestyle inflation. Define “legacy targets” that match your values—a paid-off home, funded retirement, college support, a family business, or a giving plan—and attach measurable milestones like an emergency fund level, a debt payoff date, a retirement contribution rate, and a baseline estate plan.
Before optimizing investments, get the basics stable enough that you can keep investing through surprises.
| Step | Goal | Why it matters |
|---|---|---|
| 1 | Cover essentials + minimum debt payments | Prevents late fees, credit damage, and stress-driven decisions |
| 2 | Emergency fund (starter, then full) | Protects investing consistency and reduces reliance on credit |
| 3 | Employer retirement match | Captures compensation that otherwise gets left on the table |
| 4 | Pay off high-interest debt | Locks in a risk-free “return” and improves monthly cash flow |
| 5 | Invest consistently (retirement + taxable as needed) | Compounding has more time to work when started earlier |
| 6 | Insurance + estate plan basics | Protects your assets and ensures they transfer as intended |
Momentum usually comes from contribution rate and consistency, not prediction. Many households build traction by targeting roughly 15–25% of gross income across retirement and taxable accounts, then adjusting for childcare, housing costs, or debt payoff phases.
For investing education and fraud avoidance, the SEC’s beginner hub is a strong reference point: Investor.gov.
In your 30s, your earning power can be your biggest wealth-building lever—if it’s grown sustainably.
If a structured leadership routine helps you translate performance into promotions and higher pay, consider Your Ultimate Young Leader’s Power Checklist | How to Be a Young Leader Digital Download as a lightweight, actionable add-on.
For practical consumer tools around budgeting and money decisions, the CFPB’s hub is useful: CFPB — Managing Your Money.
Building Generational Wealth in Your 30s Guide (Digital Download) is designed for the transition from “getting started” to building repeatable systems. It consolidates cash-flow setup, investing priorities, protection planning, and legacy documentation into one guided flow, making it easier to automate recurring transfers and keep a quarterly review routine.
If sleep is a limiting factor during major life transitions—especially new-parent seasons—better recovery can support better decisions. A Real-Life Guide to Better Sleep During Pregnancy (Digital Download) can help reduce friction when your household is building new routines.
A common target is investing about 15–25% of gross income across retirement and taxable accounts, starting with any employer match. If you’re facing high-interest debt or unstable income, begin lower and increase gradually as your cash flow stabilizes.
Many plans do both by capturing the employer retirement match first, then focusing aggressively on high-interest consumer debt. Paying off high APR debt is often a risk-free return, while consistent investing keeps compounding working in the background.
Core essentials typically include a will, beneficiary designations on accounts, a healthcare directive, and financial power of attorney—plus guardianship decisions if you have children. A trust may make sense when you want more control, privacy, or simplified transfers, and documents should be updated after major life events.



Leave a comment